This guide explains how Paychex 401(k) enrollment and Fidelity account services typically work, helping employers and employees understand responsibilities, eligibility, and day-to-day features. Background context covers what a 401(k) service provider does, how Fidelity recordkeeping fits into common employer setups, and what decision criteria matter when aligning payroll, benefits, and retirement administration.
If you’re evaluating Paychex 401k Fidelity for retirement administration, the very important starting point is this: the combination usually brings together payroll-adjacent plan setup support (through Paychex) and investment/recordkeeping services (through Fidelity) in a single, employer-governed 401(k) experience. Before making decisions, focus on how plan setup, participant eligibility, contribution changes, statements, and service workflows operate in your specific arrangement.
In practice, employers often choose a payroll/HR platform to coordinate plan administration and then rely on an established recordkeeper to manage participant accounts, investment menus, and reporting. Whether you’re an employer weighing vendor alignment or an employee trying to understand where contributions land, the “fit” depends on implementation details—plan documents, payroll interfaces, employer match rules, and how participant requests flow between systems.
Because this is a vendor pairing that many people discuss at a high level, it’s easy to assume the experience is standardized. It’s not. Even when Paychex and Fidelity are both present, the employer still designs the plan rules, sets the eligibility approach, decides whether Roth is available, defines match and vesting, and determines how enrollment and changes are communicated. Those choices shape what participants can do, what payroll deductions look like, and how fast updates appear.
Think of the relationship like a supply chain: payroll and HR systems “send” contribution decisions and eligibility data; recordkeeping systems “receive” that data, post contributions, and maintain the participant’s account; and the participant-facing portal ties it all together with tools and statements. When that chain is well designed and well tested, employees feel confident. When it’s not, confusion shows up as delays, mismatched balances, or difficulty getting clear answers.
From an industry perspective, the value of combining payroll-related administration (Paychex) with a recordkeeping/investment infrastructure (Fidelity) usually shows up in operational clarity. The employer does not want manual workarounds for eligibility verification, deferral changes, or remittance timing. A coordinated process reduces friction and helps participants receive consistent guidance and accurate account information.
That said, the key nuance is that the exact experience depends on how your plan has been configured by your employer and plan sponsor. Even when two vendors are involved, the employer still determines plan design (such as match formula, vesting schedules, and enrollment rules), and those plan design elements drive what participants can do and when.
Another reason this pairing matters is that it influences the “paths” participants follow for decisions. Some companies let employees change 401(k) deferrals directly in a benefits portal or payroll system; others rely on a recordkeeper portal. Sometimes both portals exist, but only one is treated as the authoritative source of the participant election. If those tools are not aligned, participants can experience uncertainty—wondering why a change made in one place did not appear on time, or why a balance update does not reflect the change yet.
For employers, the pairing can also matter from a governance standpoint. A good admin setup includes documented responsibilities, reconciliation practices, and audit-friendly reports. When Paychex and Fidelity are integrated well, the employer’s internal team can more readily verify that payroll deductions were remitted correctly, that match calculations align with the plan document, and that participant elections were processed for the right pay periods.
When researching Paychex 401k Fidelity, treat these topics as your checklist. They are the very critical drivers of participant outcomes and administrative workload.
To make this checklist even more practical, it helps to translate each item into questions you can actually ask and answers you can actually check. For example, instead of only asking “how fast will contributions post,” ask “if I submit a deferral change by payroll cutoff on a given date, when will I see it in my Fidelity account and in my paycheck stub?” Similarly, instead of only asking whether loans are offered, ask “what documentation is needed, who approves, what are the repayment terms, and how are defaults handled if payroll deductions stop?”
Another high-value area to verify is “data matching”: whether employee names, dates of hire, Social Security numbers, and addresses are transmitted correctly to Fidelity. Most participants never see this directly, but when it’s wrong, consequences can include delayed portal access, incorrect tax form delivery, or mismatched contributions. Employers and admin teams should have a process to validate employee data before elections are processed.
Even without assuming a universal configuration, the industry pattern is often similar. Paychex-related services generally align with employer-facing setup and ongoing payroll/HR coordination, while Fidelity’s recordkeeping and participant tools handle account administration and investment/trade processing.
To stay objective and accurate, it’s top to say: your exact division of responsibilities depends on the plan’s service agreement and plan documentation. Employers should request a written summary of service responsibilities during onboarding or during any vendor transition.
In many setups, the practical flow looks like this:
However, “who handles what” is not purely about technology—it's about service boundaries. For instance:
In other words, even when the vendor on the question is different, the workflow boundary matters. Clarity improves satisfaction and reduces the burden on the employer’s HR team.
A retirement plan rarely fails because of one vendor. It becomes complicated when multiple steps occur across systems—payroll submission, eligibility checks, recordkeeping acceptance, and participant instruction. That’s why employees sometimes notice timing gaps (for example, a deferral change effective on a certain payroll date but reflected on the recordkeeping site after processing).
When evaluating Paychex 401k Fidelity, ask your employer for the operational timeline that applies to your payroll cycle and your plan’s cutoffs. This is typically more helpful than generic descriptions found in online comparisons.
To understand where confusion can happen, it helps to picture the “timeline layers” that participants and employers often deal with:
Confusion commonly occurs when participants expect all layers to align instantly. For example, an employee might change their deferral rate today and assume the change affects the immediate paycheck. But if the employer’s payroll cutoff is earlier than the day the election was submitted, the change might apply next pay cycle. Similarly, the paycheck stub will show the payroll deduction change, but the Fidelity portal might show posting on a different day due to remittance processing.
Even when delays are within normal ranges, it can feel frustrating if participants aren’t told what to expect. Therefore, employers should provide a communications guide that sets expectations such as “elections apply beginning with the next payroll after cutoff” and “updates typically appear after payroll remittance and processing.”
From an employee’s point of view, the very frequent “day-to-day” questions involve accuracy, transparency, and speed of updates:
In strong implementations, employees learn a small set of repeatable facts. For example:
In weaker implementations, employees may experience what feels like “lost time” between an action and visible outcomes. The employee changes their deferral in time, sees deductions changed on the paycheck, but doesn’t see the corresponding transaction in the portal yet. Or the portal shows the transaction, but the employee is unsure why it shows a different date or amount than they expected due to how payroll remittance handles rounding or pre-tax/post-tax allocations.
Another participant issue to consider is “investment choice education.” Many employees are not experienced investors, and the plan’s education content can strongly affect their experience. If Fidelity provides an investment guide, automated features, or managed account options (depending on the plan), employees may feel more confident. If the plan doesn’t offer guided options, employees may feel overwhelmed and default to the plan’s designated default investment arrangement (which is typically defined in plan terms). Employers should communicate what happens if an employee doesn’t make an election.
For employers, the “Paychex 401k Fidelity” question often becomes a governance and implementation question: how confidently can your HR/payroll team run onboarding, monitor payroll-to-plan remittance, handle eligibility changes, and respond to employee questions without excessive manual effort?
An employer should look at:
Employers typically also need to consider the cost and burden of “exception handling.” For example, if an employee becomes eligible mid-month, what happens to payroll deductions? Is there a pro-rated approach? If an employee changes their deferral rate multiple times, how do those changes map to pay periods? If an employee is on leave, are contributions suspended? How are catch-up contributions handled if they are eligible? These are operational details that can create administrative workload if the vendor handoffs are not smooth.
Another employer concern is compliance readiness. While the vendors support operations, the employer plan sponsor remains responsible for various fiduciary and administrative obligations. These include keeping plan documents up to date, ensuring proper distribution and tax handling, and following procedures for notices and reporting. A well-structured vendor arrangement makes compliance easier by providing the necessary data, reports, and documentation.
401(k) plans are employer-sponsored retirement savings arrangements that allow employees to contribute through payroll deductions. The plan sponsor (employer) designs the plan under applicable rules, while service providers often support implementation, recordkeeping, communication, and transaction processing. In very arrangements, a recordkeeper maintains participant accounts and manages investment-related activity, while payroll systems and plan administration workflows ensure correct contributions are transmitted and eligibility is updated.
For objective context on 401(k) rules and participant rights, you can refer to the U.S. Department of Labor (DOL) and Internal Revenue Service (IRS) materials. For example, the DOL provides guidance on plan administration and fiduciary considerations, and the IRS provides tax-related retirement plan requirements. (See: U.S. Department of Labor—Employee Benefits Security Administration (EBSA); IRS retirement plan guidance.)
Reference (general sources): U.S. Department of Labor, Employee Benefits Security Administration (EBSA); IRS retirement plan guidance and published rules for defined contribution plans.
Because the question “Paychex 401k Fidelity” sometimes appears in the context of employee confusion, it’s helpful to clarify where the “real rules” come from. In most cases:
So if a participant sees an unexpected outcome—like match not applying when they thought it would—the question is not merely “which vendor.” The more correct question is “what does the plan document and the plan’s operational procedures require for that scenario?” The vendor may be doing things correctly according to the plan rules; the mismatch may be between participant expectations and plan mechanics.
The following comparison and process guidance is included to help you structure your evaluation of Paychex 401k Fidelity without relying on assumptions. Requirements and conditions vary by employer plan design, service agreements, and payroll setup.
| Evaluation area | What to compare in a Paychex + Fidelity setup | Common conditions/requirements |
|---|---|---|
| Enrollment and payroll deferrals | How participant elections are transmitted from payroll/HR workflows to the recordkeeping environment; how quickly changes appear | Defined plan eligibility rules, payroll cutoffs, data mapping accuracy between systems, and participant election effective dates |
| Recordkeeping and investment access | Balance reporting, investment selection tools, fund change requests, and transaction posting visibility | Plan investment lineup availability, transfer rules, and participant access permissions within the recordkeeping system |
| Employer match and vesting | Match calculation transparency and how vesting schedule is applied to employer contributions | Plan document match formula, true-up policies (if any), vesting terms, and employer remittance timing |
| Statements and tax reporting | Statement timing, annual tax form availability, and the clarity of transaction histories | Recordkeeping reporting cadence, plan year processing schedules, and participant contact information accuracy |
| Loans and withdrawals | Whether the plan permits loans, how applications are processed, and what restrictions apply | Plan provisions, approval workflows, eligibility for loan/withdrawal under plan terms, and required documentation |
| Support workflow | Who handles which issues (payroll contribution questions vs. account and investment questions) | Service agreement scope, escalation path, and employer-defined points of contact |
To expand on “conditions/requirements,” here are specific examples of the kinds of details that often matter in real life:
These aren’t “vendor quirks.” They are typical compliance and plan administration mechanics. But the vendor’s ability to implement them accurately affects the day-to-day participant experience.
To make these steps feel less abstract, consider how you would “test” in real life. For example, if you’re an employee, your test might look like:
If you’re an employer, your “test” might look like:
These tests matter because they uncover timing mismatches and boundary misunderstandings before they affect real payroll and real employee savings.
Even when a company selects Paychex 401k Fidelity, certain conditions frequently affect what participants can do or how quickly they see updates:
There are also conditions that can be overlooked because they are not tied directly to Paychex or Fidelity. For example:
From an employee viewpoint, it can be helpful to ask what happens in these cases. For instance: “If I change jobs mid-year, will my final contributions be reflected immediately?” “Will my match be finalized at year-end?” These questions can prevent misunderstandings.
An industry expert would typically caution against treating vendor pairing as the primary determinant of outcome. The real determinants are plan design and operational execution: whether the employer’s plan document is clear, whether payroll-to-recordkeeping data transfer is accurate, and whether participant communications match what participants can actually do in the system.
That means your evaluation should emphasize:
A useful way to evaluate “consistency” is to ask about the known processing calendars. Many recordkeepers have standard posting rhythms and quarter/year processing deadlines. When the employer knows these timelines, they can set employee expectations more accurately. Conversely, if employees experience frequent surprises—like delayed postings or unexpected fund trading dates—the issue is usually not the vendor’s marketing. It’s the mismatch between payroll cadence and recordkeeping processing windows and how that is communicated.
Another expert consideration is participant data quality. If employee SSNs are missing or typed incorrectly, or if there are multiple identifiers across systems, recordkeeping access may be delayed. Employees can mistakenly assume the portal is broken. Employers and admin teams should have a procedure for validating and correcting employee data proactively.
Finally, consider what “good support” looks like operationally. Support is not only about having a phone number; it’s about how issues are triaged and resolved. If a participant calls and the support agent must ask the employer repeatedly for missing payroll information, resolution becomes slow. A strong setup includes escalation paths, clear ownership, and access to relevant data sources.
It generally refers to a 401(k) arrangement where an employer uses Paychex for certain administration and payroll-related setup support, while Fidelity provides recordkeeping and participant account services. The precise responsibilities can vary by employer plan configuration and service agreements.
Many plans allow changes, but effective dates typically follow payroll and system cutoff rules. Employees should confirm the timing rules with their employer and review the plan’s election procedures as shown in the participant portal or plan documents.
To reduce confusion, it’s often useful to ask two questions rather than one: (1) “When can I submit the change?” and (2) “When will it start on my paycheck?” The submission time might be later than the effective time, depending on cutoffs and how payroll elections are processed. In some plans, changes submitted after a cutoff apply to the next payroll cycle.
Posting speed depends on payroll remittance timing, plan processing schedules, and eligibility status. It’s common for there to be a delay between when payroll deductions occur and when transactions appear in recordkeeping reports.
As a practical expectation, employees typically see contributions posted after the employer remits the payroll deductions for that pay period. If the employer remits later in the week or on a specific schedule, posting in Fidelity may lag accordingly. If it appears unusually delayed, it may be related to eligibility status, data corrections, or processing schedules at the recordkeeper level.
Top practice is to route the issue to the correct workflow: payroll deduction questions often start with HR/payroll, while account statements, investment changes, and recordkeeping questions often fall under Fidelity participant services (depending on your plan’s support model). Your employer should provide the appropriate contact pathway.
As you decide where to go first, it can help to categorize the symptom:
No. Investment options are governed by the plan’s investment lineup and plan document, which the employer selects within the bounds of plan governance. Fidelity recordkeeping typically delivers and maintains access to those options.
Even though the recordkeeper might provide tools and a fund menu interface, participants should not assume that all funds they see are automatically available in their plan. Availability may depend on share class, eligibility, and plan-specific restrictions. If a participant attempts to select a fund that is not in the plan menu, the system will deny it (or redirect to an eligible option), which can reveal plan design choices.
Not necessarily. Loan and withdrawal availability depends on the plan terms. Even if recordkeeping is provided by Fidelity and administration support involves Paychex, the plan document rules determine what is offered and under what conditions.
Participants should look for the specific section in their plan summary about loans, hardship withdrawals, in-service withdrawals (if allowed), and distribution upon termination or age milestones. The existence of a recordkeeping platform does not guarantee that every plan permits every type of withdrawal.
Employees can request a summary plan description (or plan summary materials), including eligibility, match rules, vesting schedule, contribution types, loan/withdrawal policies, and any relevant notices. Employers may provide enrollment guides and plan highlights.
If you want to go deeper, employees may also request the plan summary for how elections are processed (effective dates, default investments, and timelines). While participants typically don’t need legal plan text, having plain-language documentation reduces misunderstandings.
For authoritative guidance, consult U.S. federal resources such as the Department of Labor (DOL/EBSA) and the IRS, which provide information about plan administration concepts and retirement plan requirements.
These resources generally explain the framework: fiduciary responsibilities, disclosure requirements, and tax rules. However, individual plan outcomes still depend on the plan document and employer-specific operating procedures.
Employers should confirm data mapping, payroll remittance timing, eligibility alignment, participant communication plans, and reconciliation/reporting processes. A careful transition plan reduces participant confusion and helps ensure accurate accounting.
Transition phases can introduce unique challenges. For instance:
A strong transition typically includes parallel runs, validation reports, and a participant communication schedule that explains what might look different during the transition window.
Eligibility status is determined by the plan document and employer-provided enrollment processing. Employees should check their participant portal access and any enrollment confirmations, then confirm with HR or benefits administration if there is uncertainty.
In practice, eligibility can be influenced by service date definitions, hours worked (if applicable), and any waiting period terms. If an employee believes they should be eligible based on tenure but the portal doesn’t show access or contributions, it’s worth verifying with HR whether the eligibility waiting period is satisfied and whether the employer has submitted eligibility updates to the recordkeeper.
When people search for Paychex 401k Fidelity, they’re often trying to understand whether their employer’s 401(k) experience will be smooth—how contributions flow, how investments can be changed, and how reliable statements and support are. The very objective way to evaluate fit is to move from brand names to operational specifics: plan document terms, payroll cutoff timing, participant access workflows, match and vesting rules, and the support path for common questions.
If you want, tell me whether you’re approaching this as an employer (plan setup/administration) or an employee (enrollment/contributions/investments), and I’ll tailor a tighter checklist of what to ask and where timing usually shows up.
And if you’re currently in the middle of enrollment or plan changes, consider doing one “documentation pass” right away: gather the plan summary materials, confirm the effective dates and contribution election timing rules, and save the contact pathways for payroll issues versus account/investment issues. That simple step can turn a confusing process into a manageable one—because most 401(k) frustrations are not about the existence of Paychex or Fidelity, but about when and how your specific election and contributions become visible in the system.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You
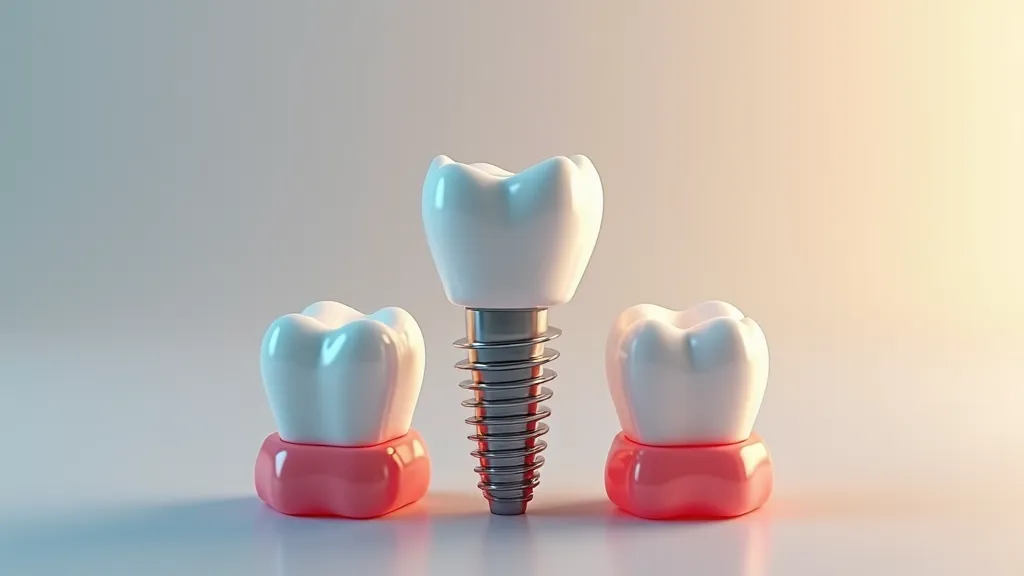
Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Exploring the Retipster Club Advantage
The Retipster Club is an invaluable resource for real estate investors, offering a plethora of insights, tools, and community support to boost investing endeavors. Aimed at helping both novice and seasoned investors, the club provides educational materials, success stories, and expert strategies tailored to the ever-evolving real estate market landscape. Dive into this analysis to understand the manifold benefits the Retipster Club offers to enhance real estate success.
Navigating the Retipster Club
This article delves into the unique offerings of the Retipster Club, a community designed for individuals interested in real estate investment, providing educational resources and networking opportunities. Discover how the club supports its members through expert advice, comprehensive guides, and a robust community platform, all tailored to foster insightful and profitable investment strategies.
Pmoc Abrava: Practical Procurement and Quality Considerations
This guide explains how to approach Pmoc Abrava procurement with a quality-first, compliance-minded process. “Pmoc Abrava” is discussed as a term used in sourcing contexts, covering typical decision factors such as specification clarity, supplier capability, documentation, and handling requirements—using an objective framework for safer purchasing, risk control, and consistent performance.
Unveiling Grunig & Hunt's PR Models
This article explores the seminal work of Grunig & Hunt in developing models of public relations. The Grunig & Hunt models, fundamental to understanding PR theory, provide insight into the strategic approaches and methodologies utilized in the field. Each model offers a distinctive perspective on communication and engagement strategies, relevant to both academic discussions and practical applications.
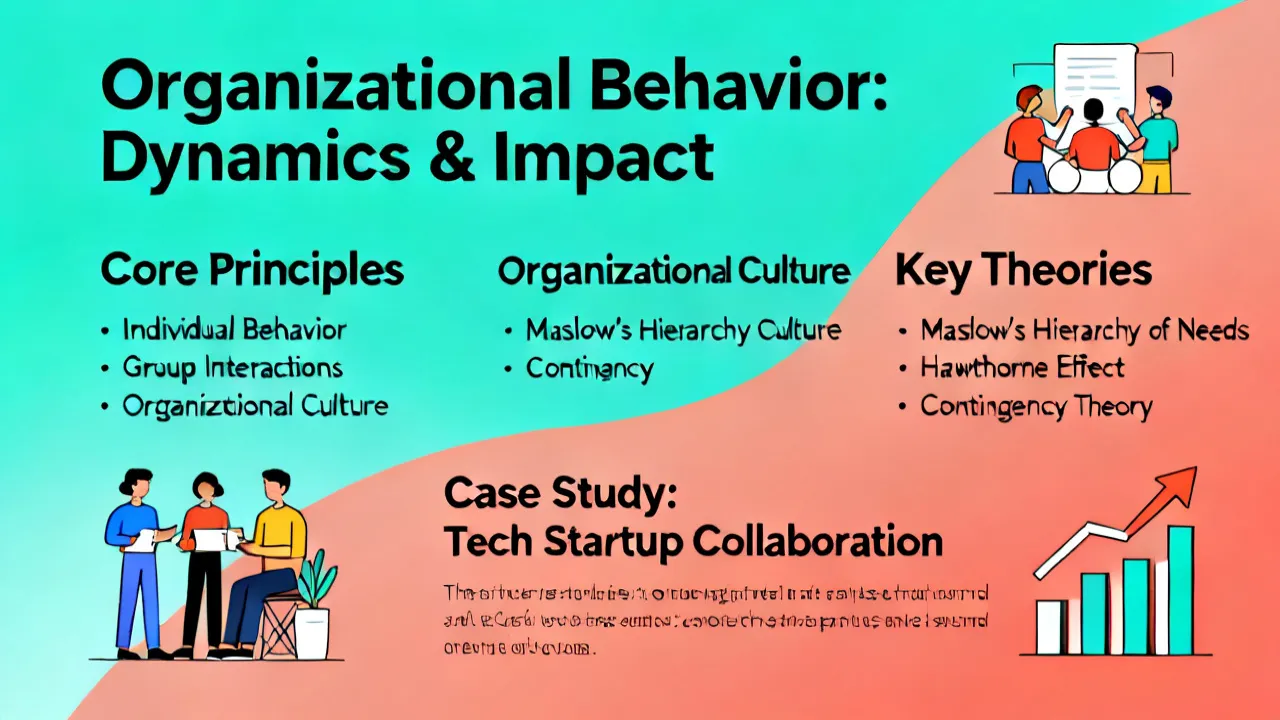
Understanding Organisational Behaviour Slideshare
This article delves into the significance of Organisational Behaviour Slideshare for both educators and professionals. Organisational Behavior is a field that examines the impact individuals, groups, and structures have on behavior within organizations, aiming to improve an organization's effectiveness. With Slideshare's platform, these insights are easily shared, promoting a collaborative learning environment.
Understanding Ltda Epp for Supplier and Compliance Decisions
Learn how “Ltda Epp” impacts supplier selection, contract structure, and compliance planning. This guide explains, in objective terms, what the label typically signals in company registration and how it can affect procurement processes, risk checks, and document readiness. It also frames practical conditions, comparison points, and decision steps to help you evaluate suppliers with clarity and consistency.