This guide explains how Gusto Health Insurance works, what employers typically evaluate, and how employees can choose plans with confidence. It provides objective background on how employer-sponsored health coverage is structured, why eligibility and plan design matter, and which documentation steps reduce surprises during enrollment and renewals.
When you’re comparing Gusto Health Insurance options, the very important question isn’t only “What does it cost per month?” It’s whether the plan’s coverage design (deductibles, copays, coinsurance, provider networks) aligns with how you and your household actually use care—doctor visits, prescriptions, preventive screenings, urgent care needs, specialty consults, lab work, mental health services, imaging, and any expected procedures. From an industry perspective, employers and employees usually get better outcomes when they compare total out-of-pocket expectations across the year rather than focusing on a single premium figure.
Because health insurance is regulated and plan offerings can vary by state and employer setup, the very reliable approach is to review plan materials provided during enrollment and confirm details with the plan administrator. Below, you’ll find an expert, structured evaluation framework—plus requirements and practical decision steps—so you can compare options responsibly.
It also helps to remember a common real-world dynamic: the cheapest-looking premium can become expensive once you reach the deductible, once you begin using higher-cost services, or once prescriptions land on non-preferred tiers. Conversely, a plan with a slightly higher premium can be financially favorable if it has a lower deductible, stronger prescription coverage, or a richer network that keeps most visits in-network at predictable rates. A disciplined comparison makes it less likely that you’ll choose based on assumptions.
Gusto Health Insurance generally refers to health coverage offered through an employer benefits workflow associated with the Gusto platform. In many employer-sponsored models, the employer plays a role in selecting benefit options, contributing a portion of premiums (if applicable), and guiding employees through eligibility and enrollment. Meanwhile, employees choose among available plan tiers and must understand how costs change when care is used.
Even when a platform streamlines enrollment, the underlying medical coverage still follows standard health insurance concepts: deductibles, network rules, prescription tiers, prior authorization processes (when applicable), and medical necessity requirements. For objective clarity, think of Gusto Health Insurance as a route to benefits administration rather than a separate insurance product with a single universal price.
In other words, when you see “Gusto” mentioned, it usually indicates how you access the plan selection and enrollment experience—not that the medical benefits themselves are identical across all employers or locations. Two employees can both enroll “through Gusto” and yet receive plans that differ significantly in network breadth, cost-sharing structure, drug formulary design, and reimbursement rules.
Healthcare spending patterns vary widely, but many budgeting errors come from overlooking the same few plan components. As an industry analyst would advise, begin with:
This approach helps you compare Gusto Health Insurance options in a way that’s consistent with how claims are processed, not just how premiums are marketed.
To make this more practical, you can treat these “invisible drivers” as a checklist you can translate into a budgeting forecast. Premium is only the monthly fee for access; deductibles, coinsurance, and drug tiers are often what shape your real annual experience.
Health insurance benefits are often time-sensitive. Missing a window can mean waiting until an annual enrollment period—or until a qualifying life event triggers special enrollment. In practice, employers using benefits platforms typically communicate:
From a risk-management standpoint, employees should treat enrollment like a compliance task: confirm eligibility, read the Summary of Benefits and Coverage (SBC) or equivalent, and verify network access before committing. Timing mistakes can lead to gaps in coverage, delays in access to services, or surprises about which date of service is covered.
One nuance that often matters: some plans require coverage to be active before certain prior authorizations or drug coverage decisions take effect. If you’re starting a medication, scheduling surgery, or continuing therapy, confirm that your plan selection is effective when you need it—otherwise you might face delays or denials.
Plans are typically priced using a monthly premium, but that premium is only one component. Two employees can pay similar premiums yet experience very different year-end costs depending on deductibles, service utilization, and prescription needs. An objective comparison should therefore look at:
If you are seeing “price information” cited in external places, treat it as informational only. For the very accurate figure, use the official plan documents made available through your enrollment process, since pricing can change by plan year and by eligibility group.
A practical budgeting method is to compute two rough totals for each plan: (1) a “low utilization” estimate (e.g., a couple of office visits and routine prescriptions) and (2) a “moderate utilization” estimate (e.g., more specialist visits, lab work, imaging, a couple of higher-cost claims). Even if these are not exact, they help reveal which plan’s cost structure is less punishing under your household’s likely patterns.
In employer benefits ecosystems, the “supplier” side typically includes multiple parties: insurers (or health plan carriers), network administrators, pharmacy benefit managers (PBMs), and benefits administration partners. When discussing Gusto Health Insurance, it’s useful to distinguish:
For an objective due-diligence check, employees should always confirm the carrier name and the exact plan tier shown in the enrollment portal or plan booklet. This prevents mix-ups between similarly named products and ensures the comparison is apples-to-apples.
It’s also wise to understand where to go when something goes wrong. If a doctor’s office says a claim was denied, you typically need to know whether the issue is medical coverage, network status, coding rules, or prior authorization. If prescriptions cost more than expected, the PBM’s formulary rules may be the controlling factor rather than the medical plan’s general descriptions.
Another subtle point: some plans have separate deductibles or cost-sharing requirements for pharmacy benefits vs medical benefits. Others may integrate them. Your plan documents should specify how drug costs apply to overall out-of-pocket limits (and whether all drug types count toward the OOP max, depending on the plan design).
Health insurance is not standardized in the way many consumer products are. Even among plans with similar premiums, differences in network, drug coverage, and cost-sharing can lead to markedly different outcomes. Industry reporting and regulatory materials consistently emphasize that plan choice should be grounded in benefit structure and network fit, not advertising-level price alone. For example:
Practical takeaway: If you want reliable decisions, base them on the official plan documents provided during Gusto Health Insurance enrollment rather than secondhand descriptions.
Complexity shows up in edge cases: network changes during the year, drug formulary updates, coverage rules that differ by tier, and claim adjudication policies. A disciplined comparison reduces your exposure to these “surprise” situations.
Below is a structured approach you can apply whether you’re an employer choosing options for your team or an employee comparing plans.
Done this way, your decision becomes repeatable and defensible—exactly what benefits operations teams aim for when guiding enrollment. It also reduces stress, because you’re not scrambling to interpret plan language after a service has already been performed.
The table below summarizes major decision elements relevant to Gusto Health Insurance-style employer coverage. It is intentionally practical and written to reduce ambiguity during plan selection.
| Decision factor | What to check in plan documents | Why it matters | Common pitfall |
|---|---|---|---|
| Network | In-network hospitals/clinics, specialist access, referral rules, and out-of-network policy | Network status often determines whether claims process at preferred rates | Assuming a doctor is covered without confirming the plan’s network |
| Deductible | Annual deductible amount and whether services are subject to it | Controls when cost-sharing begins for many services | Comparing plans solely by monthly premium |
| Copays/coinsurance | How visits, imaging, procedures, and therapies are cost-shared | Predicts member costs for typical usage | Ignoring coinsurance after the deductible |
| Out-of-pocket maximum | OOP cap for covered in-network services | Sets a worst-case member spending ceiling | Not recognizing whether certain charges count toward OOP max |
| Prescription coverage | Formulary tiering, copay/coinsurance, and authorization rules | Medication costs can dominate annual spending | Discovering a drug is excluded or requires prior authorization after enrollment |
| Eligibility timing | Waiting periods, hire-date rules, and effective date schedules | Determines when coverage begins and what’s covered immediately | Missing enrollment deadlines or dependent submission timelines |
| Employer contribution | How much the employer contributes (if any) and how it affects net premium | Changes the real monthly cost to employees | Overlooking employer contribution changes year over year |
| Preventive care rules | Covered preventive services, coding rules, and any limitations | Helps you plan routine checkups safely | Assuming every “routine” visit is coded as preventive |
| Prior authorization & step therapy | Criteria for expensive drugs/services, approval processes, timelines | Can delay care or change the cost outcome | Not allowing time for authorization before starting treatment |
| Claims processing and billing | How claims are filed, typical turnaround references, and dispute/appeal steps | Influences how quickly you resolve issues | Not keeping paperwork and explanation-of-benefits records |
| Coordination of benefits (COB) | How the plan coordinates with other insurance, including dependent coverage | Prevents duplicate coverage surprises | Assuming there is no COB impact when multiple insurances exist |
Requirements vary by employer policy and by plan design, but in employer-sponsored health coverage programs, the conditions below are commonly encountered. Use them as a checklist when reviewing your own Gusto Health Insurance enrollment materials.
Understanding these conditions helps you avoid the two most common enrollment problems: (1) coverage not active when you think it is, and (2) paperwork issues preventing dependents or specific plan elections from taking effect.
Gusto Health Insurance typically refers to employer health insurance benefits offered through a benefits administration experience associated with Gusto. The specific medical plan terms—cost-sharing, networks, and prescription rules—come from the underlying health plan carrier and plan documents available during enrollment.
It’s helpful to locate your carrier name, plan ID, and summary document inside the enrollment portal. Those items tell you what the rules actually are, regardless of platform branding.
No. Premiums and employee contributions can vary based on plan tier, eligibility group, location, employer contribution structure, and whether coverage is employee-only vs family coverage. For objective accuracy, confirm the current figures in the official plan selection materials provided for your employer’s enrollment period.
Also, premium price can change year to year—even if plan names stay similar—so comparing only the previous year’s costs is not enough.
Use a structured approach: verify in-network access, compare deductibles and OOP max, review prescription formularies for your medication list, and estimate “low” and “moderate utilization” scenarios.
When possible, ask for (or download) the SBC and the formulary information. Then you can compare apples-to-apples across each component.
Many plans include coverage for certain preventive services when delivered per plan and applicable regulatory rules. Exact coverage details depend on the plan design and service coding. Always check your plan’s summary and benefits documents.
Additionally, preventive coverage can be impacted by how a provider codes the visit. If the visit includes a problem unrelated to preventive care, cost-sharing may apply for the non-preventive portion.
You may need to wait until the next open enrollment period unless you qualify for a special enrollment event due to a life change (for example, certain changes in household or employment). Confirm qualifying events and deadlines in your plan communications.
Some special enrollment events require documentation submission within a specific timeframe. If you miss that deadline, the election may not take effect.
It depends on whether your doctor is in-network for the specific plan tier you choose under the health plan’s network. Confirm directly using the network information provided during enrollment or in the official plan resources.
Even if your doctor is generally “in-network,” you should verify they participate under the specific plan product and whether referral rules apply.
Prescription costs depend on the plan’s drug formulary tiering and pharmacy benefit rules. Some medications may require prior authorization or step therapy. Reviewing your medication list against the formulary is the very reliable method.
Also consider whether your plan uses generic substitution rules, quantity limits, or specialty pharmacy arrangements. These can affect both your out-of-pocket costs and the convenience of obtaining refills.
Coverage terms can differ for employee-only versus dependent coverage. Contributions and plan costs also often differ by coverage tier. Use the enrollment materials to confirm how each option is priced and what benefits apply.
Additionally, coordination of benefits can arise if a spouse or partner has their own coverage. In that case, the two plans determine who pays first and how cost-sharing is calculated.
Because Gusto Health Insurance arrangements can differ by employer setup and plan year, avoid relying on informal claims about specific prices, guaranteed savings, or universal carrier features. Instead, anchor decisions in official documents, network confirmations, and a realistic view of cost-sharing. This is consistent with top-practice benefit education approaches and consumer-protection goals reflected in U.S. health plan disclosure frameworks.
Also, be cautious with statements like “Plan X always covers everything” or “Plan Y is always cheaper.” Plan costs can be unpredictable for households with variable utilization. The best approach is to forecast based on real usage patterns and to understand the cap (OOP max) that limits in-network spending.
If you are ever uncertain, it’s appropriate to ask your employer benefits team or plan administrator for clarification. Many employers can also provide a benefits comparison worksheet or help interpret plan documents.
For readers who want additional objective context on plan comparison and health insurance disclosure, consider reviewing materials from U.S. government agencies such as:
These sources provide relevant standards on how coverage terms and benefit information should be communicated, which supports informed comparison during enrollment.
While employer plans can be more customized than public exchanges, the general transparency principles—like using standardized summaries and disclosing cost-sharing rules—remain a helpful framework for evaluating options.
Choosing Gusto Health Insurance is easiest when you treat it as a structured decision: verify the network, compare deductibles and out-of-pocket maximums, confirm prescription coverage for your medication list, and check eligibility and effective dates. With that framework, you can evaluate plan options objectively and reduce the risk of unexpected costs—whether you’re an employee planning for routine care or an employer aiming for predictable benefits administration.
Ultimately, the “best” plan is the one whose design matches your household’s real needs, within your comfort level for risk and your expected use of healthcare services. When you base your choice on documented plan terms instead of impressions, you gain clarity now—and you avoid costly confusion later.
Striking the Perfect Balance: Navigating Premiums and Out-of-Pocket Expenses in Senior Insurance Plans
Explore the Tranquil Bliss of Idyllic Rural Retreats
How to Make Lasting Memories at Disneyland Attractions
4rkojvsx Technology: Industry Insights and Buying Guide
Affordable Phones and Plans for Seniors
Affordable Full Mouth Dental Implants Near You

Unlock the Top Kept Secrets to Finding Your Ideal Dentist for Flawless Dental Implant Results!
Discovering Springdale Estates
Unveiling RS Sul Telecom Services
Pet Insurance Essentials: Coverage, Costs, and Resources Explained
In recent years, pet ownership has seen a significant surge. Pets, whether they're dogs, cats, birds, or other animals, have increasingly become integral parts of our families. With this growing bond, there is a rising awareness of the importance of pet health and well-being. Just as health insurance is crucial for humans, pet insurance is becoming an essential consideration for pet owners. This article aims to provide a comprehensive understanding of pet insurance, covering its importance, types of coverage, associated costs, and valuable resources to help you make an informed decision.
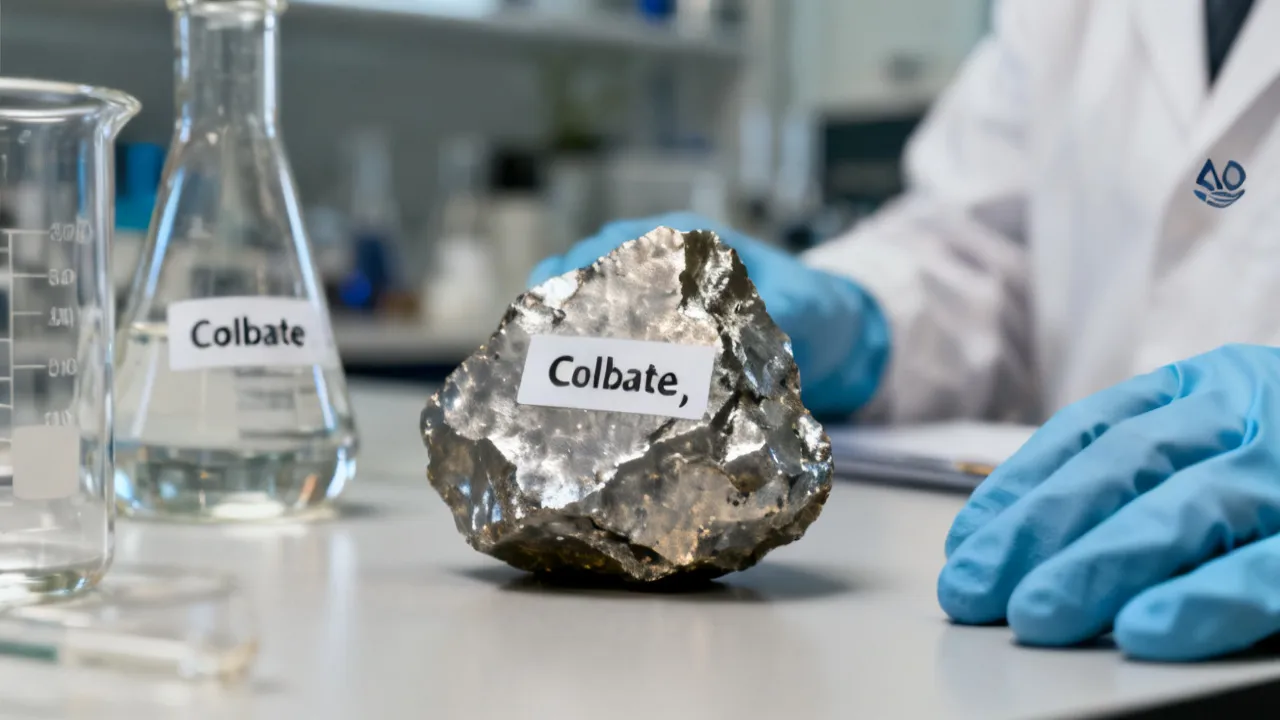
Colbate Explained: Uses, Sourcing, and Top Practices
This guide explains Colbate from a practical industry viewpoint, covering what it is, how suppliers typically handle it, and what buyers should verify before purchase. It also summarizes objective background on related terminology, common application considerations, and due-diligence steps. Readers will find a comparison table, requirements, and targeted FAQs to support confident sourcing decisions.
Strategies for Financial Security and Legacy Planning
Life insurance isn't just about what happens after you pass—it's a strategic tool in a comprehensive plan for your financial security and estate planning.
Navigating Insurance Costs for Seniors: Essential Tips and Advice
As we age, healthcare costs and the complexity of managing them can become increasingly burdensome. For many seniors, navigating insurance costs is a crucial aspect of ensuring financial stability and maintaining health. This guide aims to provide you with essential tips and advice on how to manage and potentially reduce these costs effectively.
Discovering Dunlop Brooklin Footwear
This article delves into Dunlop Brooklin, a prominent name in the footwear industry known for its exceptional quality and innovation. Dunlop is recognized for its wide-ranging collection of shoes designed to meet diverse customer needs, from casual wear to professional attire. This guide provides an in-depth analysis of Dunlop Brooklin and its offerings, revealing why it stands out in the market.
Your Guide to Understanding Car Insurance Coverage
Navigating car insurance can be puzzling. Fortunately, this guide illuminates coverage types and choosing the right provider.